After hail or high wind hits Combine, the right order of operations protects both your roof and your insurance claim: document first, stop active leaks with proper tarping, get a written professional inspection, and only then make claim decisions.
STORM TRIAGE
What do you need help with right now?
Pick the door that matches your situation. It routes you to the right person on the team, and every path starts with a free, documented look at the roof.
Texas law requires homeowners to pay their insurance deductible.
Cedar Crest does not waive or absorb deductibles. If anyone offers to, walk away.
It puts your claim at risk and may be illegal. We document damage, provide estimates,
and meet your adjuster on-site to answer construction questions. We are not a public
adjuster and do not interpret your policy or negotiate claim value.
We document storm damage in Combine with photos and measurements, provide written estimates, and meet your adjuster on-site to answer construction questions. We are not a public adjuster: we do not interpret your policy or negotiate claim value. Texas law draws that line and we respect it. And we never offer to waive deductibles; that practice is illegal in Texas.
Roofing in Combine, specifically
Combine sits in the metroplex’s Kaufman County ring, where the roofing inventory reads differently than the inner suburbs: more acreage and semi-rural properties, more metal roofing on homes as well as shops and outbuildings, and building departments whose permit requirements are often lighter than the big-city versions but still worth knowing cold. Crews route here on scheduled windows rather than same-hour dispatch, storm response covers structures the inner-ring never thinks about (barns, shops, carports), and the free inspection covers all of it in one documented visit.
The same crews cover Kaufman, Terrell and Forney, which keeps Combine scheduling flexible when storm weeks compress everyone’s calendar.
FROM OUR CREWS
The crews you'd actually get.
Real Cedar Crest crews on DFW roofs. Every project photo below is from our own jobs.
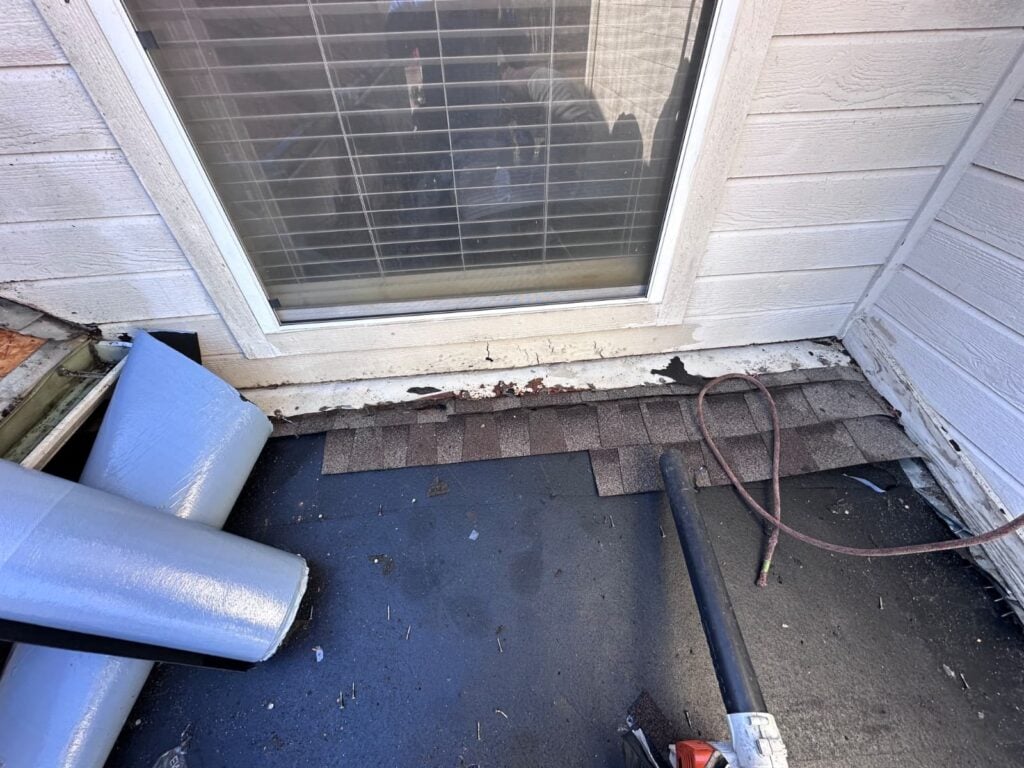
Before the call
Weathered, lifted, and worn, documented before any work.
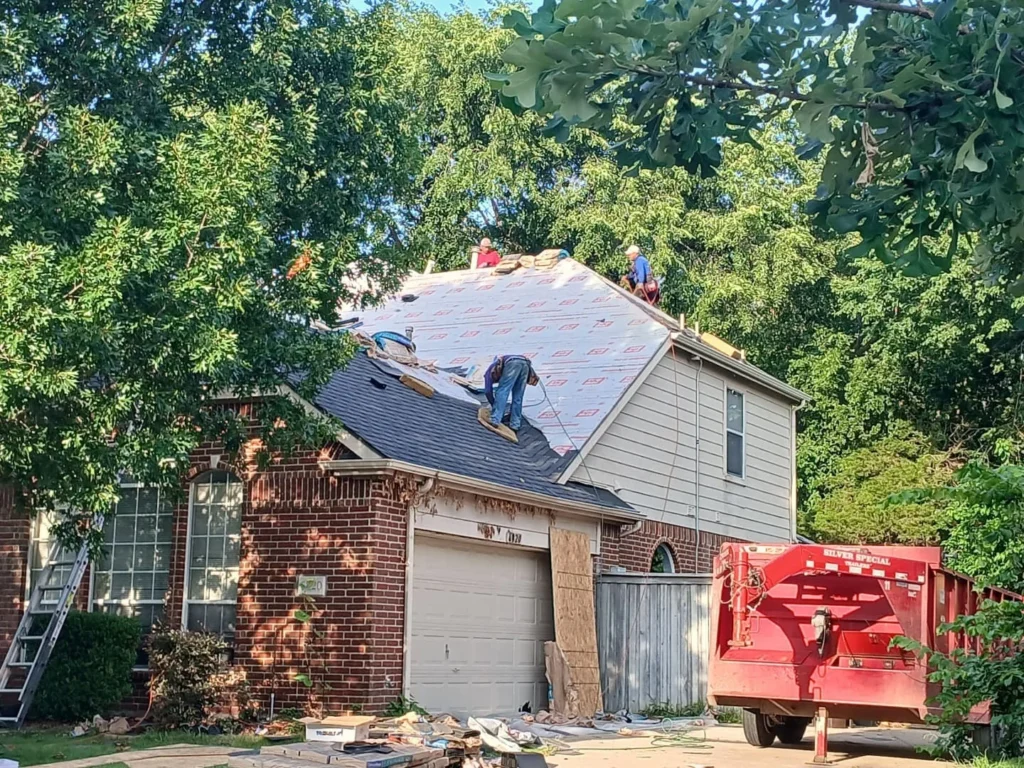
On the slope
A Cedar Crest crew mid-installation on a DFW re-roof.
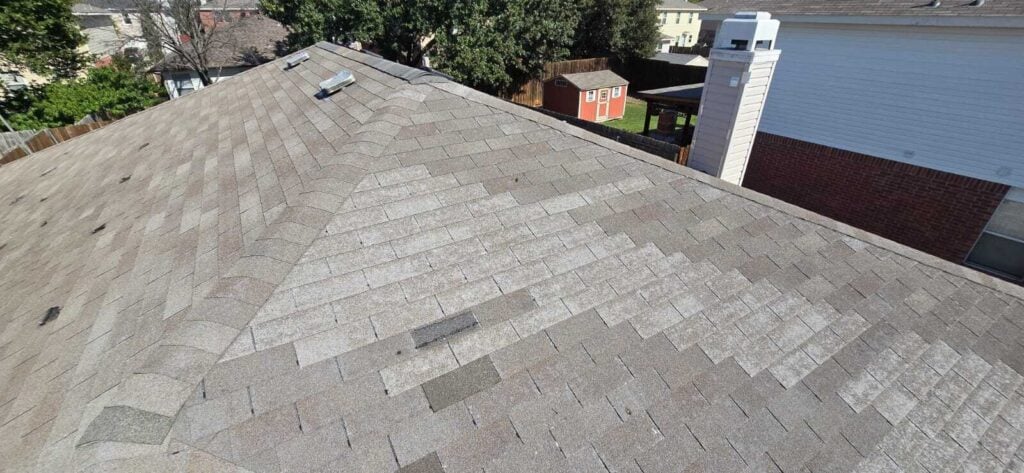
Closed up and cleaned
A finished architectural asphalt system with the site cleared.
PUBLIC RECORD
The hail and housing record in Combine
Before you plan storm & hail damage in Combine, it helps to know what the public record says about local hail and the age of the homes.
6
Hail days, 1 in.+ since 2006
3
Golf-ball-size hail days
2.75 in.
Largest stone on record
1990
Median year homes built
Hail near Combine
Reported hail is less frequent around Combine: NOAA lists 6 days since 2006 with hail one inch or larger within 5 miles. Fewer reports can also reflect fewer storm spotters in smaller communities, so a quiet record is not a guarantee. Hail that size was reported in 5 of the last 20 years. The largest stones on record nearby measured 2.75 inches (baseball size) on May 24, 2011. The most recent report: 1-inch hail on May 16, 2025.
May 24, 2011: 2.75-inch hail (baseball size)
May 17, 2010: 1.75-inch hail (golf ball size)
February 5, 2008: 1.75-inch hail (golf ball size)
May 16, 2025: 1-inch hail (quarter size)
March 23, 2013: 1-inch hail (quarter size)
How old Combine homes are
The median home in Combine was built in 1990, and 20% of the city's 874 housing units predate 1980. Many of these houses are likely on their second roof or nearing the point where they need one.
Sources: NOAA National Centers for Environmental Information, Storm Events Database (hail reports since 2006 within 5 miles of Combine); U.S. Census Bureau, American Community Survey 2020–2024 5-year estimates. Data pulled September 2026.
We don't waive deductibles; nobody legally can. Texas law requires
homeowners to pay their insurance deductible (Tex. Ins. Code ch. 707). If a roofer offers
to "cover" or "absorb" yours, walk away. It puts your claim at risk and may be a felony
for the contractor.
We document damage, provide repair and replacement estimates, and meet your
adjuster on-site to answer construction questions. We are not a public adjuster
and do not interpret your insurance policy or negotiate claim value on your behalf.
Common questions about storm & hail damage in Combine
How do I know if my roof in Combine has hail damage?
Ground-level clues include dented gutters and vents, but the damage that matters (shingle bruising and granule displacement) needs an on-roof inspection. Ours are free and documented with photos.
Should I file an insurance claim after every storm in Combine?
No. File when documented damage justifies it. An inspection first protects you both ways: real damage gets properly documented, and a healthy roof avoids an unnecessary claim on your record.
A door-knocker offered to cover my deductible. Is that legit?
No. Texas law requires homeowners to pay their deductible, and contractors offering to waive or absorb it are breaking the law and putting your claim at risk. Walk away.
How fast can you get to Combine for this work?
Scheduled windows run reliably. Crews route the ring on planned days rather than same-hour dispatch, with genuine emergencies jumping the queue regardless of geography. You'll get honest timing on the first call.
How often does hail hit Combine?
NOAA lists 6 days since 2006 with hail one inch or larger within 5 miles of Combine. Smaller communities have fewer storm spotters, so reports tend to undercount what actually falls. The most recent report was 1-inch hail on May 16, 2025.
How old are most homes in Combine?
The median home in Combine was built in 1990, according to the U.S. Census Bureau's American Community Survey. 20% of the city's housing units predate 1980 and 11% were built in 2010 or later. Many homes here are reaching the age when original roofs come due.